MORTGAGE NEWS
VantageScore 4.0 Is Now a Mortgage Score. Start With Your Free Credit Scores.
Updated October 12, 2026 · By Dan Frio, Mortgage Loan Originator, NMLS #246527
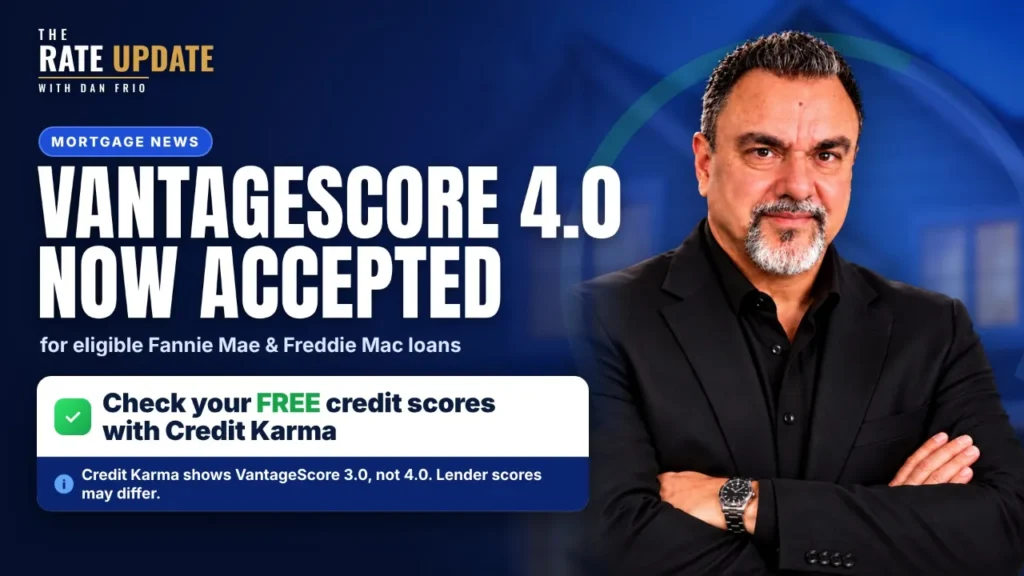
Since September 2026, every lender approved by Fannie Mae and Freddie Mac can qualify eligible loans with VantageScore 4.0 or Classic FICO. Your lender picks one model for your loan, and many still use FICO. Either way, the smartest first step is the same: know where your credit stands before a lender pulls it.
Buying a home? Start with your FREE credit scores.
I’m Dan Frio, host of The Rate Update. I check my own credit with Credit Karma, and it’s where I tell first-time buyers to start. It’s free, there’s no credit card, and checking won’t lower your score.
I use Credit Karma myself, and this is an affiliate link: Credit Scores and More may earn a commission if you sign up, at no cost to you. Credit Karma isn’t affiliated with The Rate Update or PBT Bancorp.
Score lower than you hoped? Watch this first.
Six credit fixes you can start in the next 30 days, from a loan officer with 38 years in mortgages (13 min).
Which credit score do mortgage lenders use now?
For decades the answer was FICO. Now lenders selling loans to Fannie Mae and Freddie Mac can choose either model, loan by loan:
- Classic FICO: FICO Score 2 (Experian), FICO Score 4 (TransUnion) and FICO Score 5 (Equifax). Still accepted, with no retirement date announced.
- VantageScore 4.0: from Equifax, Experian and TransUnion, for loans run through Fannie Mae’s Desktop Underwriter or Freddie Mac’s Loan Product Advisor.
A few rules matter for buyers. The lender uses one model for every borrower on the loan. Manually underwritten loans still require Classic FICO. Lenders still pull all three bureaus and typically use the middle score. And lenders are allowed to use 4.0, not required to, so ask yours which one it will use.
What changed, and when
- July 8, 2025: FHFA announces lenders may use VantageScore 4.0 or Classic FICO for Fannie Mae and Freddie Mac loans.
- April 22, 2026: A limited rollout of VantageScore 4.0 begins.
- September 3, 2026: The FHFA Director announces that all approved lenders may use VantageScore 4.0.
- September 9, 2026: Fannie Mae (Lender Letter LL-2026-06) and Freddie Mac (Bulletin 2026-H) make it official for every approved lender.
- October 1, 2026: Fannie Mae and Freddie Mac price loans the same whether the lender uses VantageScore 4.0 or Classic FICO.
- October 8, 2026: FHA issues Mortgagee Letter 2026-11, adding VantageScore 4.0 and FICO 10T alongside Classic FICO.
- January 1, 2027: FHA loans can use VantageScore 4.0 for case numbers assigned on or after this date. FHA minimum scores stay the same, and every borrower on a loan must use the same model.
Credit Karma’s free score vs. your mortgage scores
| Score | Bureaus | Where you can see it | Who uses it |
|---|---|---|---|
| VantageScore 3.0 | TransUnion and Equifax on Credit Karma | Free on Credit Karma and most free score apps | You, to track your credit. Not a mortgage score. |
| VantageScore 4.0 | All three | Few consumer sites yet. Your lender sees it if it uses this model. | Lenders on eligible Fannie Mae and Freddie Mac loans |
| Classic FICO (2, 4, 5) | All three | myFICO (paid plans) | Most mortgage lenders today, and all manually underwritten loans |
The same credit report can produce different numbers in each model. That’s why a free score is the right first look, not the final word.
VantageScore 3.0 vs. 4.0
They are separate models built on the same three-digit scale (300 to 850). VantageScore 4.0:
- Looks at up to two years of trends in how you use credit, not just a single snapshot.
- Leaves out medical collections and paid collections.
- Uses machine learning to score more people with thin credit files, and counts rent and utility payments when they’re reported to the bureaus.
Credit Karma shows 3.0, so treat it as a close-enough check on your direction, not your exact mortgage number.
Where can you check VantageScore 4.0?
Few consumer sites show it yet. Most free score sites, Credit Karma included, show VantageScore 3.0, so ask your loan officer for the scores from your mortgage credit pull. Your lender will see your 4.0 scores if it uses that model when it pulls your credit. To see the FICO scores most lenders still pull, go to our myFICO guide.
How to build the data VantageScore 4.0 counts
VantageScore 4.0 can count your rent and utility payments, but only when they show up on your credit report, and most landlords and utilities never report them. VantageScore’s own research found that adding rent and utility payments raised scores for people with thin or inactive credit, by as much as 80 points for some who had not used credit in six months or more. Results vary, and it only helps if you pay on time.
Report your rent and utility bills
CreditScoreIQ adds rent and utility payment reporting, plus 3-bureau credit reports and scores and unlimited dispute letters. $39.99/mo.
See CreditScoreIQ →Build history with every payment
Self is a credit builder account that reports each on-time payment to the credit bureaus. Self can also report the rent you already pay.
Start With Self →Add a credit builder account
Credit Strong lets you make monthly payments into savings, and those payments are reported as on-time payment history.
See Credit Strong →Watch all three bureaus
TransUnion Credit Premium gives you quarterly 3-bureau scores and reports, plus daily 3-bureau monitoring and alerts. $29.95/mo.
See TransUnion →We may earn a commission if you sign up through these links, at no cost to you. Prices are as listed by each company on October 19, 2026 and can change. The scores these services show are VantageScore 3.0. Your lender pulls the score it uses for your mortgage.
Your 3-step credit check before you apply
- Free scores first. Check your free credit scores on Credit Karma and look for errors or surprises.
- See all three bureaus. MyScoreIQ shows reports and scores from all three, so you can catch an error on one bureau before a lender does.
- Know the score you need. Read the credit score needed to buy a house, then ask your loan officer, “Which score model will you use on my loan?”
Know your scores? Shop your mortgage the smart way.
One application. One credit pull. 30+ lenders compared, from Dan Frio of The Rate Update.
Compare Home Loan OptionsBook a Free ConsultationDan Frio | NMLS #246527 | PBT Bancorp | NMLS #257781. Mortgage products are originated by PBT Bancorp, NMLS #257781. Equal Housing Lender.
Frequently asked questions
Does Credit Karma show my mortgage credit score?
No. Credit Karma shows free VantageScore 3.0 scores from TransUnion and Equifax. Mortgage lenders pull all three bureaus and use Classic FICO or VantageScore 4.0, so your mortgage score can be higher or lower.
What is the difference between VantageScore 3.0 and 4.0?
They are separate models. VantageScore 4.0 looks at up to two years of trends in how you use credit, leaves out medical and paid collections, and can score more people with thin credit files. Since September 2026, 4.0 is accepted for eligible Fannie Mae and Freddie Mac loans.
Where can I check VantageScore 4.0?
Few consumer sites show it yet. Most free score sites, Credit Karma included, show VantageScore 3.0, so ask your loan officer for the scores from your mortgage credit pull. Your lender sees your 4.0 scores if it uses that model when it pulls your credit.
Does checking my credit score hurt it?
No. Checking your own score is a soft inquiry and never lowers it. Only a lender’s hard pull for a credit application can.
Does a credit score mean I’m approved for a mortgage?
No. A score is one part of approval. Lenders also look at your income, debts, savings, the property and the loan program. A pre-approval from a lender is the way to know.
Sources
- FHFA: Credit Scores
- Fannie Mae Lender Letter LL-2026-06
- VantageScore: free credit score providers
- Credit Karma: free credit score
- HUD Mortgagee Letter 2026-11
- VantageScore: rent and utility data study